Stamp Duty Land Tax (SDLT) is payable in England on residential property transactions where the market value is more than £125,000. SDLT uses a tiered scale related to the purchase price. Different rules apply if you’re a first-time buyer or resident overseas, buying an additional home or buy-to-let, or buying through a company. Non-residential property transactions are subject to different rates, presently lower than residential rates.
The HMRC consultation spotlights tax calculations in two key areas:
- transactions using the Multiple Dwelling Relief rules; and
- those involving mixed-use purchases of both residential and non-residential property.
Multiple Dwelling Relief (MDR)
Under the present rules, you can claim MDR when at least two dwellings are purchased in a single transaction or as part of a series of linked transactions between the same vendor and purchaser.
MDR allows the SDLT rate to be calculated based on the average value of each dwelling (calculated individually and then added together) rather than on their combined value.
For example, rather than calculating stamp duty on a single transaction of three properties at a total cost of £1.5 million, the tax could be calculated on three individual properties valued at £500,000 each. This method can enable significant savings as stamp duty rates are scale-tiered according to the property value.
Mixed-use purchases
Purchasers can make savings when claiming for mixed-use purchases. This is because mixed-use purchases attract a lower non-residential SDLT rate (even when the amount of non-residential land in the purchase is tiny).
HMRC highlights that mixed-use purchases can range from:
- B&Bs
- country houses with some land let for grazing
- fast food shops and pubs with flats above
- large-scale city centre developments which comprise ground floor retail outlets with floors of apartments above.
Because mixed-use purchases fall into the non-residential class, purchasers can benefit from the lower non-residential rate of SDLT. They can also avoid surcharges when an individual already owns residential property or currently lives overseas.
Also, mixed-use purchases can be combined with MDR whilst still qualifying as non-residential. Unlike MDR claims involving only residential property, which would be calculated to include any surcharges payable by existing residential property owners or non-UK residents.
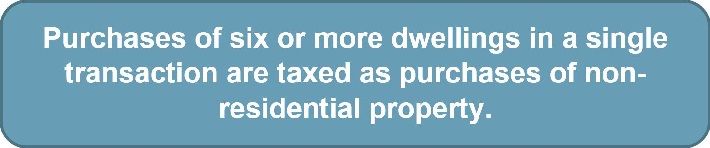
For SDLT purposes, there is a definition of what a ‘dwelling’ means and deciding whether it qualifies. HMRC use several indicators, such as whether there is a separate council tax bill and energy supply, a lockable front door, or the facilities needed to live independently, such as a toilet or washing facilities.
Residential property partner at RIAA Barker Gillette said:
“Change is undoubtedly coming, and there may be a motivation to move on with any purchases where you may be able to claim these reliefs.
When stamp duty was introduced, the tax charges on residential and non-residential property were similar, so there was no significant tax advantage, but now there is a big difference once property values are over £1m, or where higher rate additional dwelling rates apply.”
He adds:
“However, this is a complicated area and it’s worth getting specialist professional advice on the topic. Mixed-use purchases and MDR is not automatic and must be claimed through a land transaction return. Non-specialist conveyancers may not be aware of the potential to make a claim, or what constitutes a legitimate claim and HMRC will push back on anything that is misrepresented.”
The consultation document outlines some examples of non-residential usage claims rejected by HMRC, including a room above a detached garage used as an office by the purchaser when part of a large, detached, six-bedroom home; leasing the garage of a suburban, semi-detached property to a company for storage; and a paddock area behind the back garden of a substantial residential property in an affluent location being used for informal grazing by a neighbour’s horse.
Note: This article is not legal advice; it provides information of general interest about current legal issues.